
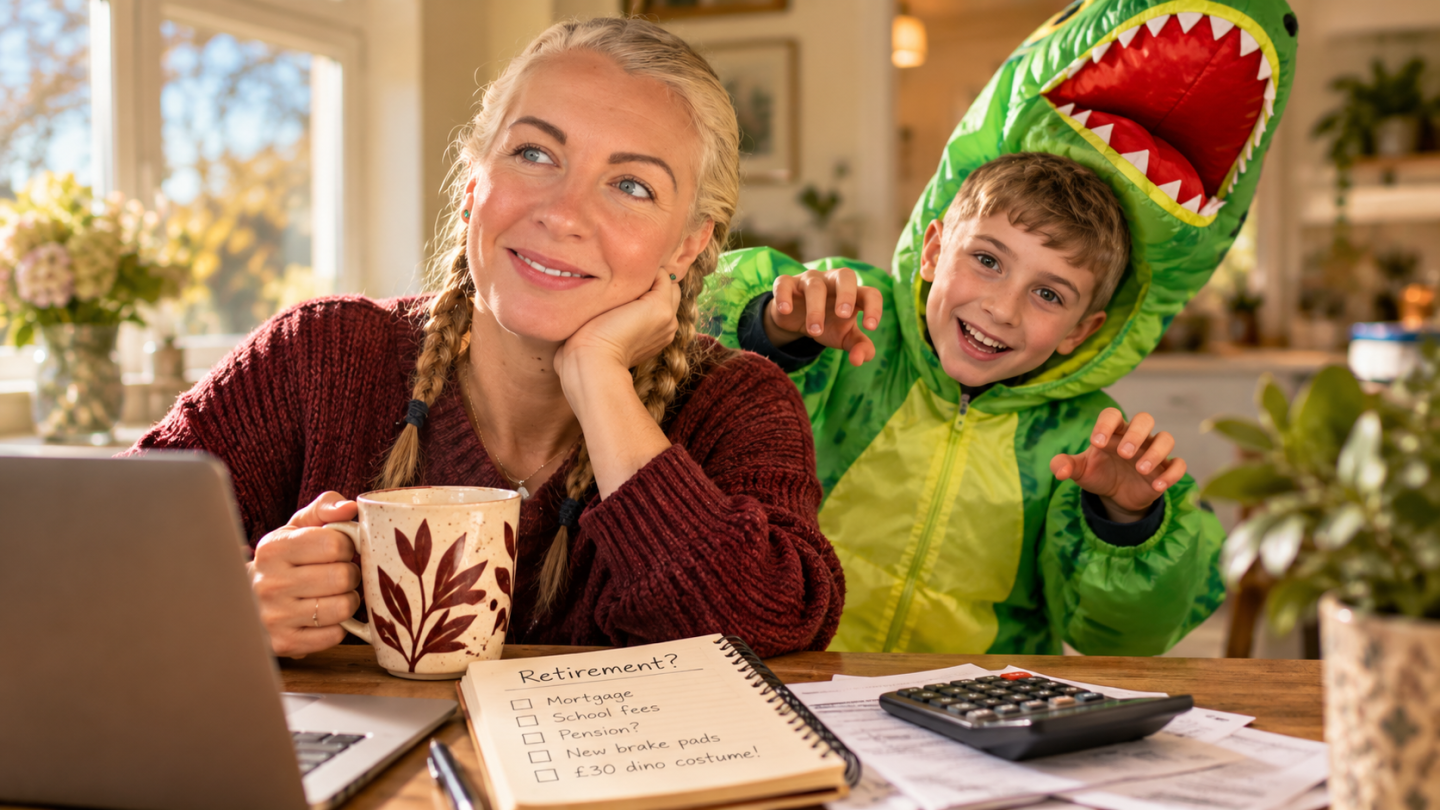
Do we live for today or save for a retirement we might never see?
In a YouGov survey for Mattioli Woods, UK adults estimated they would need an average household income of £42,456 a year after tax to retire comfortably. With a mortgage, private school fees and a ten-year-old to raise, I’m wondering how we’re supposed to afford the future while paying for the present.
Retirement is getting uncomfortably close
When I was younger, retirement sounded lovely. Finish work, collect a pension, take up gardening and enjoy holidays without checking the annual leave allowance. These days, H and I are more concerned about affording a replacement oven. At 51, retirement is not a distant event involving an elderly version of myself wearing sensible shoes. It’s an everyday topic of conversation, alongside the mortgage, Cyrus’s school fees, the price of diesel and whatever has broken in the house.
And I’ll admit something. Retirement scares the living daylights out of us. We both love working, but neither of us has a clear plan for how we’ll afford to stop. So when I saw the figure, I wondered where the hell that money was supposed to come from.
How are we supposed to save for retirement when we’re still paying for the present?
The sums are daunting, especially when there is no obvious point at which family expenses become smaller.
The mortgage, school fees and a £30 dinosaur costume
I had Cyrus at 40. When he turns 18, I’ll be approaching 60, potentially helping him through further education while preparing for retirement. We have private school fees, a mortgage and other bills. Then there are our gym memberships, which are essential for our physical and mental wellbeing, although the direct debits suggest otherwise.
Recently, the roof needed repairing, the oven broke and the car needed new brake pads. None of these expenses was welcome, but swearing under our breath in Farsi and ignoring them wasn’t an option. Cyrus, meanwhile, believes our financial difficulties can be solved by just working more hours. That way, we’ll still be able to afford the £30 inflatable dinosaur costume he’s demanding for Halloween. Apparently, all his friends are getting one. Financial planning is very straightforward when you’re ten.
Even my gym coffees are under investigation
I recently discovered I’d spent approximately £500 on coffee at the gym over a year. That works out at roughly £42 a month, a figure I might have ignored if I hadn’t seen the annual total. Of course, somebody will suggest putting that money into a pension instead. Sensible advice, but I enjoy sitting down with a coffee after exercising. It’s often the only quiet moment I get between work and family responsibilities. Could I spend less? Absolutely. I’ve started taking a flask, although I resent how financially responsible that makes me feel.
What does a comfortable retirement cost?
The YouGov survey for Mattioli Woods found that UK adults put the figure at £42,456 a year on average, or £3,538 a month, in today’s money. Younger adults aged 18 to 24 estimated £55,272 a year, compared with £36,252 among those aged 55 and over.
There were regional differences, too. Londoners expected to need £53,292 annually, while respondents in the North East estimated £32,232. Living in Newcastle, I appreciate that housing can cost less than in London. Unfortunately, supermarkets don’t offer regional discounts, and heating bills aren’t sympathetic to our postcode. These figures reflect people’s expectations, not recommended retirement income targets. What feels comfortable depends on individual circumstances, whether the mortgage has disappeared and the children have stopped needing financial assistance. I suspect our roof will still find ways to demand money when we’re 70.
What happens if we can’t keep working?
The survey found that 33% of respondents worried about losing income or becoming unable to work, while 39% were concerned about unexpected health or long-term care costs. Those figures resonate with me. Perimenopause has made me very conscious that good health isn’t guaranteed. I love exercising and intend to remain active, but there’s no certainty that either of us will be physically capable of working indefinitely.
And there’s an important distinction between choosing to continue working because you like it and having no choice because your pension won’t cover the bills. For women who’ve taken career breaks to raise children, retirement planning can be really complicated.
What if we never get to enjoy retirement?
What if we spend another 15 years postponing holidays and scrutinising every expense, only for illness or circumstances to change our plans? I want us to be financially secure in old age, but I also want Cyrus to remember family adventures, not a childhood governed entirely by pension contributions.
So maybe we should start by examining our pensions properly rather than treating retirement as something we’ll sort out eventually. MoneyHelper’s pension calculator offers a way to estimate our retirement income, while the government’s State Pension forecast service can help establish what we might receive.
I still haven’t worked out the perfect balance. We’ll continue working, saving what we can and enjoying family life without feeling guilty about every purchase. The coffee flask is staying, though. And that remote desert island occasionally sounds tempting. No mortgage, school fees or brake pads. Just H, Cyrus and me, living off coconuts. Although knowing my luck, we’d discover the island had a gym with an expensive coffee shop.
So, what would you choose? Save more for a comfortable retirement, or spend a little now making memories with the people you love?
More from Saffron & Cyrus
Come along for the ride.
Occasional stories, experiments, discoveries and questions from Saffron & Cyrus.
NB: No spam. Just stories, discoveries and the occasional big question. You can unsubscribe whenever you like.
Discover more from Saffron & Cyrus
Subscribe to get the latest posts sent to your email.

Saffron & Cyrus is an independent women’s editorial publication with a recognisable voice, real-life perspective, a defined midlife audience and a commercial model built around useful, relevant partnerships.
